
Could your living annuity cost less and give you more income?
If your living annuity costs more than your medical aid, it's time to switch.
Is your living annuity working hard enough for you?
If you have a living annuity, the decisions you make around your income, investment strategy and fees can have a significant impact on how long your retirement savings last.
Understanding your EAC reveals the full cost of investing, helping you make informed decisions and avoid fees that reduce your savings. The Effective Annual Cost (EAC) introduced by ASISA gives you a complete comparison of all investment costs, including investment management, advice and administration charges.
Your retirement income is too important to ignore fees
Does your retirement cost more than your medical aid?
2.5% × R7 500 000
R15 625 p/m
A 2.5% total annual fee on a R7.5 million living annuity
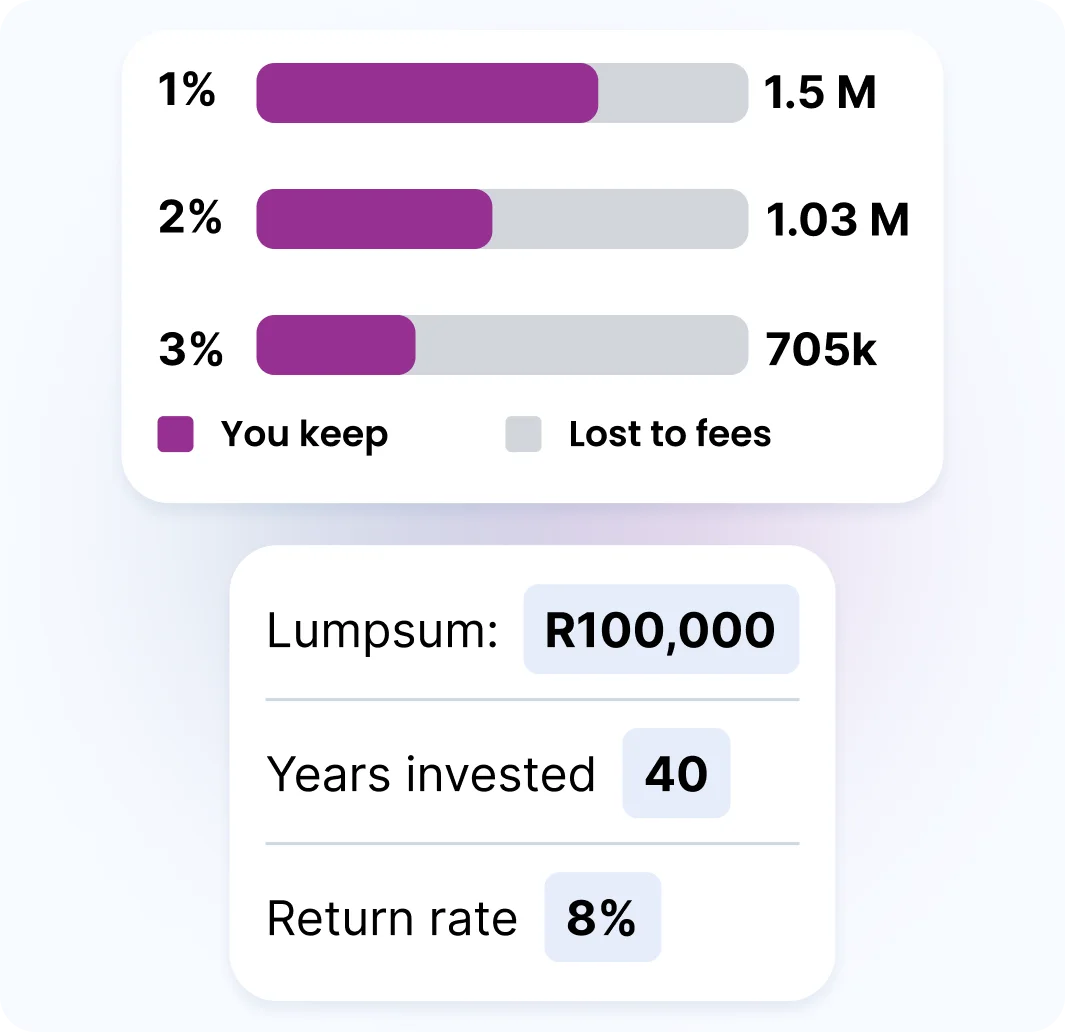
For a large living annuity, even what looks like a relatively small annual fee can translate into tens of thousands of rand leaving your retirement investment every year.
Know the rand value of your investment fees and compare what you're paying with what you're getting in return.
And because fees are charged repeatedly, their effect compounds over time.
We unpack how returns, fees and withdrawals fit together further down.
Fees that work for you
Our fees are simple and transparent, so you know exactly what you're getting in your investment.
| Investment value | Annual 10X fee |
|---|---|
| First R5 million | 0.86% |
| Next R5 million | 0.57% |
| Above R10 million | 0.40% |
Fees can impact whether your savings last your retirement years or not. At 10X, we aim to keep fees as low as possible.
Estimated annual fee:
0.86%Will your money last?
One of the biggest questions in retirement is also one of the simplest:
How much can I afford to withdraw without putting my future income at risk?
With a living annuity, you can choose an annual income of between 2.5% and 17.5% of your investment value.
Your retirement outcome comes down to a simple relationship:
Ask yourself:
Am I withdrawing too much?
Can my current income keep up with inflation?
How long does my money need to last?
Video: Building blocks to a lasting living annuity
You can view the transcript or key points covered in this blog post.
Could I take the same income while paying less in fees?
Use our calculator to get an estimate of how much monthly income you could receive.
Reasons to switch: How do I know I'm in the right living annuity
A living annuity should give you a sensible investment strategy, flexibility over your income and transparent, competitive costs.
Look at the whole picture
When reviewing your living annuity, ask:
What am I paying in total fees?
How has my portfolio performed over the long term?
Am I invested appropriately for my age and income needs?
Is my money diversified?
How easy is it to change my income or investment portfolio?
Do I understand what happens to my investment when I die?
The right living annuity isn't necessarily the one that produced the highest return last year. It's the one that suits your income needs and lets you keep more of your long-term return after fees.
Switching to 10X is easy - speak to one of our consultants.
Speak to an investment consultant
Speak to an investment consultant
Real assistance by real people
No chatbots, call centres or weeks waiting for a response. Our team is here to help via email or phone.Easy switching
We'll fully manage the switch from your old provider.Clear product information
We'll explain our products and funds so you can make the best choice for you. No advice, just the facts.
How do I protect my retirement investments?
Is your retirement capital protected?
Protecting your retirement savings doesn't mean avoiding investment risk completely.
Your retirement could last 20 or 30 years, which means part of your money may still need to grow long after you stop working.
The challenge is finding the right balance.
Three things matter
Your drawdown rate
How much you're taking out.
Your investment return
How hard the money left behind is working.
Your fees
How much of that return you actually get to keep.
9 out of 10 people do better with 10X
Low returns and high fees can significantly reduce your retirement savings. At 10X, we keep your fees low and our 10X Your Future Fund consistently outperforms benchmarks.
Additionally, we offer offshore investments to help you diversify your portfolio and protect your retirement income.
Validate whether you could do better with 10X. Our free comparison report breaks down historical performance and fees, so you can make an informed decision.
Choose the best 10X fund for you
The following funds are available with a living annuity. Need help choosing a fund? Use our Fund selection tool
Need help finding the right fund?
Use our fund selection tool to see what fund is best for your needs