How will my retirement look if I don’t become a best-selling author?
26 October 2026
The views and opinions expressed in this article are those of the author and do not necessarily reflect the official policy or position of 10X Investments.
Benjamin Franklin made famous the line that nothing is certain except death and taxes.
And he’s right. In my case, although I pay my taxes on the same schedule as everyone else, death could come faster, depending on the mood of the Killer Cat™.
The Cat’s Claw of Damocles is no excuse not to plan for retirement, because whether I’m living out my last days in my beach cottage or hiding in a seaside safehouse from a murderous feline, it’s all gonna cost money. Planning for retirement is also a neat way of providing impetus for tax calculations. So.
Let’s give myself a bit of a reality check, and assume (ludicrously, obviously) that I’m not going to the next JK Rowling - let’s live the nightmare of my as-yet-unwritten books crashing and burning. It seems obvious I’m going to have to find some way of earning a living. Singing for my supper, so to speak, except I can’t sing.
(Maybe people will give me money to stop singing?)
Plan for a comfortable retirement with our
Living Annuity calculatorMaths: still not my strong suit
Let’s say I currently spend R50,000 a month. Let’s also assume I have paid off a house and have a nice little bicycle to get to and from the shops because I live in a village, and have managed to eliminate some expenses – remembering also that my medical aid has got more expensive because I am, inconveniently, older now.
To replace that R50,000 in today’s money, at compound inflation of an assumed 5%, I’d need almost R130,000 a month in 25 years. Ouch, that is a nasty number.
(Inflation was 4.4% in August having come down from 5% in June, so I think my estimation is a fair one)
I plugged my numbers into the 10X calculator – based on 75% of current earnings, so I don’t drop dead of a heart attack before I need to work out how much to save – and it tells me I currently have around 7% of what I need. That’s a…big… shortfall.
Which means I best find some money from somewhere. For the sake of convenience, I’ll work in today’s money and not the crystal ball figure of almost R130,000, which will also be a lot less frightening.
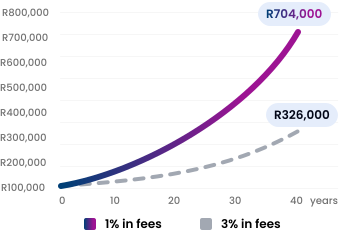
Higher fees very likely means lower returns (and here's the maths to prove it)
Paying high fees on your retirement investments (such as a retirement annuity or a living annuity) almost always means less money in your pocket, and less money for your retirement. Read more
Glamorous options await
There won’t be all that many job options available to me, at least not many artificial intelligence (AI) can’t do (which might explain why my book hasn’t become a bestseller – perhaps AI has already written a better one).
I could become a cashier. According to Indeed, the average cashier in South Africa earns around R5,400 a month, which is a rather miserable 14% of the R37,500 I need. It would also be absolute hell on my replaced knees, which I suspect would object rather strongly to standing behind a till for eight hours a day.
Still, I would only need to work almost seven full-time cashier jobs to make up the money. I haven’t quite worked out how to fit that into a 24-hour day, but I’m sure there’s a spreadsheet somewhere that can help.
Building blocks to a lasting Living Annuity
Our panel of experts discusses living annuities, sustainable drawdown rates, offshore investing, and everything else one might need to consider to ensure a comfortable retirement. Read more

Alternatively, I could become a receptionist. Indeed puts the average salary at around R7,800 a month, which is better for the knees but still leaves me with a rather substantial problem.
And I suspect answering phones all day would interfere with my plans to persuade my book agent that I can still become a bestselling novelist if I just tweak a few things here and there instead of rewriting. Again.
I could also become a barista, which would bring in around R6,400 a month, according to Indeed. That’s about 17% of what I need, and I’d be back on my feet all day. There is also something particularly depressing about the idea that I could spend my retirement making coffee for people who are sitting on the beach, instead of being one of them.
How I’m beating inflation’s impact on my children’s (and grandchildren’s) inheritance
Inflation is the silent destroyer of the value of our money (and our retirement savings!). But Business Times journalist Nicola Mawson isn't taking that lying down - she's fighting back. Read more
Numbers that add up to nothing
Bookkeeping is a more promising option when it comes to money, with average earnings of around R15,800 a month. That gets me to about 42% of what I need.
However, it also requires actual bookkeeping skills, especially considering I needed AI to create a spreadsheet for me that shows a pipeline of work, work I can invoice, and how much cash I should (or not) have at the end of the month. And assuming someone is prepared to employ me.
Still broke, just more qualified
What I’d actually quite like to do is lecture. After decades of journalism, and four degrees, I reckon I have a few things I could teach students, not least of which is how to annoy people by asking questions they would rather not answer.
Indeed puts the average lecturer’s salary at around R32,500 a month, which would get me to almost 87% of what I need. Now we’re talking. My chances of actually getting employed are probably decent too - I just need a PhD first so I can become Dr Annoying Journalist. (Hint, hint, Wits).
And before anyone starts pointing out that salaries will be higher in 25 years, that’s precisely why I’m doing this bit of the exercise in today’s money. I’m also assuming that the expenses I won’t have in retirement really have disappeared, rather than finding new and exciting ways of haunting my bank account.
Which leaves me with the rather unpleasant conclusion that even if I find a job after retiring, I may still not earn enough to afford retirement. So, I best talk to people who actually understand this stuff.
Related articles
How can we 10X Your Future?
Begin your journey to a secure future with 10X Investments. Explore our range of retirement products designed to help you grow your wealth and achieve financial success.